Do lenders re-check self-employed income before closing?
Lenders re-check your job or business before closing. What self-employed buyers in escrow should hold steady, what can stop a loan, and who to ask first.

In this article
- Your lender looks at your work or business one more time days before closing, even after you've been approved.
- If your job or business changes while you're in escrow, the loan can stop, so ask me first.
- On a closed-end mortgage, your Closing Disclosure, the form with your final loan terms, must reach you at least three business days before closing under a Consumer Financial Protection Bureau (CFPB) rule.
- As a broker, I treat one lender's no as one lender's answer and can shop your file across a network of wholesale lenders.
Does the lender check my job again before closing?
Yes. Lenders re-check your job in the days before closing, and for a self-employed buyer that means your business and the income you applied with.
Your approval is a green light based on what your file looked like on the day the underwriter signed off. The lender takes one more look before funding, and that look covers whatever pays your bills.
Why does the lender look again when I'm already approved?
Your approval rests on the income you showed when you applied, and the lender confirms that income still exists before the money moves. Escrow takes time. A business can change a lot before you sign.
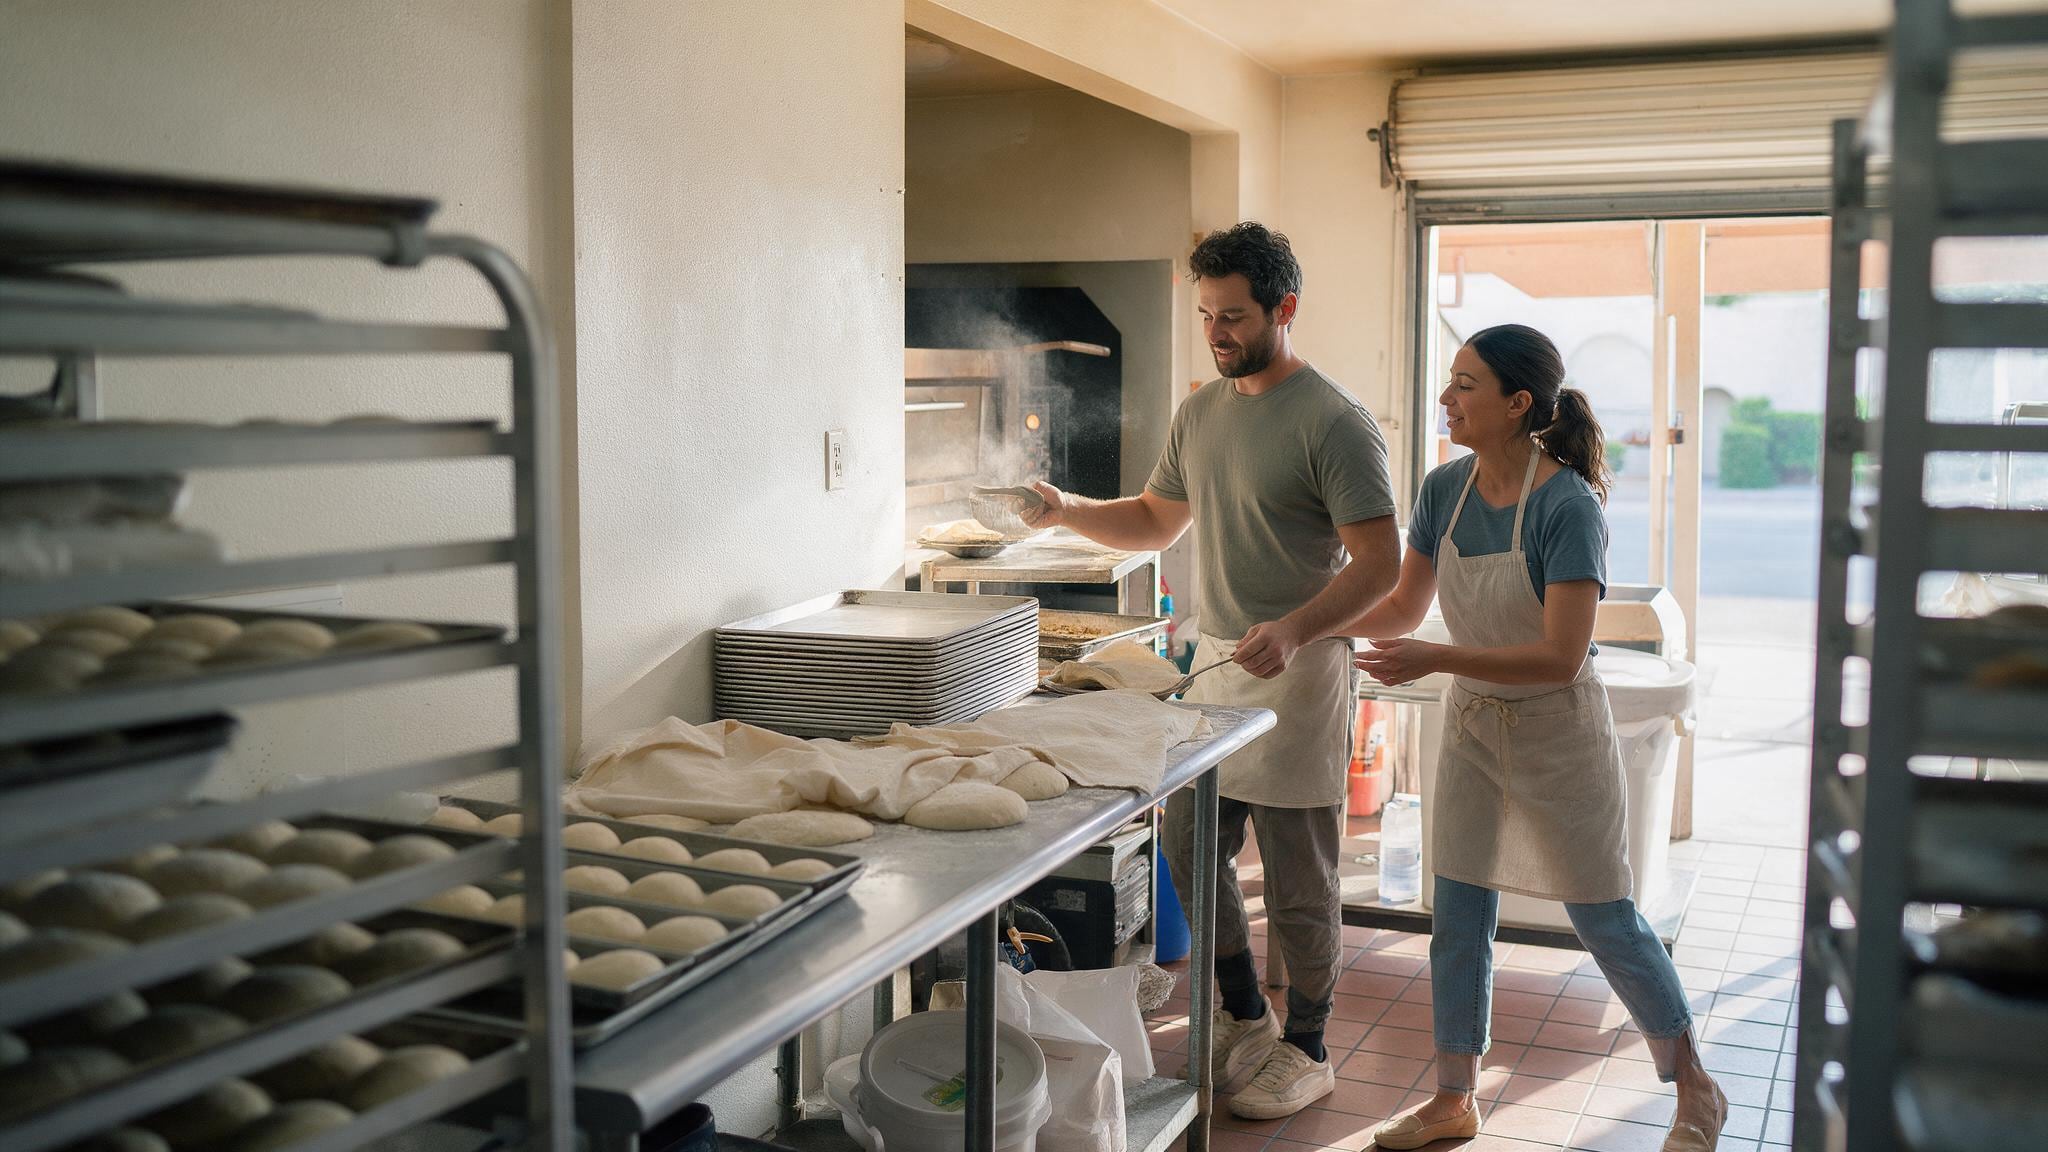
For a business owner, the last check usually looks at whether the business that produced this income is still running. I close bank-statement loans and asset-based loans that retail banks turn away, so the income you qualified with can come from statements instead of returns.
Federal rules set one more date. Under the CFPB's Regulation Z, your Closing Disclosure has to reach you at least three business days before closing. That's your window to read the final terms. It also means your file is nearly done, so a change that late hits hard.
That timing rule covers closed-end mortgages only, not home equity lines of credit (HELOCs) or reverse mortgages.
| When | What happens |
|---|---|
| Days before closing (no set day count) | Lender re-checks your job, or your business and income if you're self-employed |
| At least three business days before closing | Your Closing Disclosure must reach you (closed-end mortgages only, per CFPB Regulation Z) |
| Closing day | You sign the final loan documents |
What changes during escrow can stop the loan?
A new job, fewer hours or quitting during escrow can stop the loan. For a self-employed buyer, a drop in business income or a change to the business works the same way. Closing the business can change the income your approval rested on.
Say your loan matches the example below. When the lender re-checks your income, that income still has to cover this payment, plus taxes and insurance.
| Example loan term | Amount and monthly payment |
|---|---|
| Home price | $500,000 |
| Down payment | 20% ($100,000) |
| Loan amount | $400,000 |
| Term | 30-year fixed, 360 monthly payments |
| Rate | 6.1% (6.171% annual percentage rate, or APR), as of January 29, 2026 |
| Monthly principal and interest payment | $2,423.98 |
Example: a $400,000 30-year fixed loan at 6.1% (6.171% APR) with 20% down ($100,000) on a $500,000 home has 360 monthly payments of $2,423.98 in principal and interest. The APR assumes 0.75 discount points ($3,000, the median paid by 2023 home buyers who paid points, according to the CFPB) and no other lender fees. Taxes and insurance are not included, so the actual payment will be higher. The rate is the market average for January 29, 2026 from Freddie Mac Primary Mortgage Market Survey; yours depends on your credit, loan and property.
A change can stop a loan, but it doesn't always. Tell me before you act, because I can check whether a different lender's rules still fit the file. Different lenders want different deals. I can't promise one will say yes, but asking first keeps your options open.
Myth or fact: self-employed buyers and the last check
One bank's rules aren't the whole market. I'm a broker, so I shop one file across a network of wholesale lenders instead of living by one bank's rulebook.
- Myth: lenders hate self-employment. Fact: each lender writes its own rules, and I close bank-statement and asset-based loans that retail banks turn away.
- Myth: approved means done. Fact: the lender re-checks your work or business days before closing.
- Myth: only tax returns count. Fact: some lenders can use business bank statements when your returns show less than you make.
- Myth: one no ends it. Fact: I'm a broker, so I can shop the same file to other wholesale lenders.
- Myth: small changes slide by. Fact: even a cut in hours can stop a loan in escrow, so a new business setup or a big client leaving is worth a question first.
How I know this
I've done this work for 21 years, and as a broker I shop one file across many lenders instead of one bank's rules. I once helped a self-employed contractor whose bank said no because his returns showed about half what he earned. We used twelve months of business bank statements, found a lender that liked the deal, and he closed. The disclosure timing comes from the CFPB's Regulation Z.
What should I do before I sign?
Until your loan funds, keep your business, your income and your job the way they were when you applied. If any of them might shift, text me first.
- Ask me how a change affects the file before you make it, from a new job to a contract that ends early.
- Have your recent business statements and income records ready in case the lender asks.
- Read your Closing Disclosure when it arrives and compare it line by line with what you expected.
- If your income shifted, run your numbers on my site's free calculators, which show the real payment in a few minutes with no credit pull.
When you tell me about a change, I look at whether it affects the file and which lender's rules still fit. Sometimes nothing moves. Sometimes the file needs a different lender. I can't promise the outcome, only that we see it early.
Questions about taxes or how your business is set up belong with your CPA.
If anything about your business, hours or job could change before your loan funds, tell me first and act after. Nothing changing? Keep your income steady, keep your records ready and read your final terms when they arrive. If a lender already said no because of a change, I can ask other lenders in my network whether the file fits theirs. Send me your question and your numbers right here on this page, no pressure.
Questions people ask
Do lenders check employment again right before closing?
Yes. Lenders re-check your job days before closing. If you're self-employed, that check looks at your business and the income you applied with.
Can changing jobs or cutting my hours during escrow stop my loan?
Yes, a job change or a cut in hours during escrow can stop the loan. Ask me before you make the change, and I'll look at whether the file still fits this lender or another one.
What if I resign or close my business while I'm in escrow?
A resignation in escrow can stop the loan, and closing your business can change the income your approval rested on. Talk it through with me before you do either. Questions about taxes or business structure go to your CPA.
Spot something out of date? Tell Sophia.
More like this
Bank-statement loans: how self-employed buyers qualify when their tax returns show less than they make
Your tax returns aren't the only way to prove what you earn. Here's how lenders use your deposits instead, what it costs, and what to do before you look at a house.
Sophia Warner · Sep 26, 2026 · 4 min read
Divorced and self-employed: what a lender reads before you buy
One San Diego file from decree to underwriting: what the lender read first, when support counted as income, and what self-employed buyers should ask.
Sophia Warner · Jan 29, 2026 · 8 min read
Student loans in your DTI: each loan type has its own rule
FHA, VA, conventional and USDA loans can count an income-driven student loan payment differently. See what goes into DTI and what to ask each lender.
Sophia Warner · Jan 27, 2026 · 5 min read